Ship and offshore engineering observation
1. The event itself
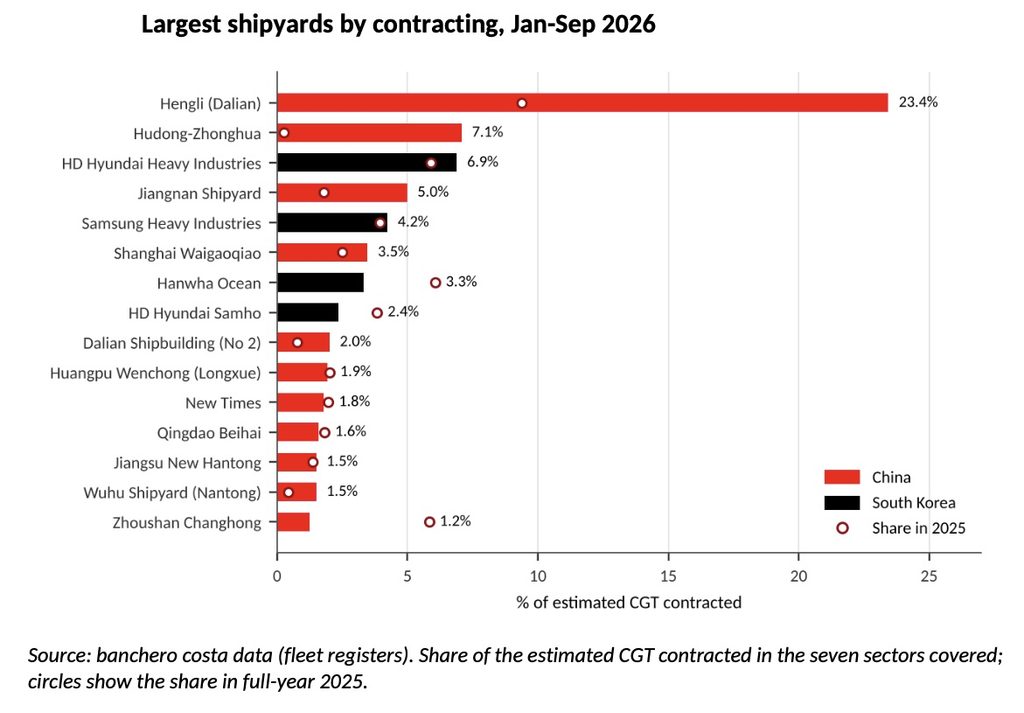
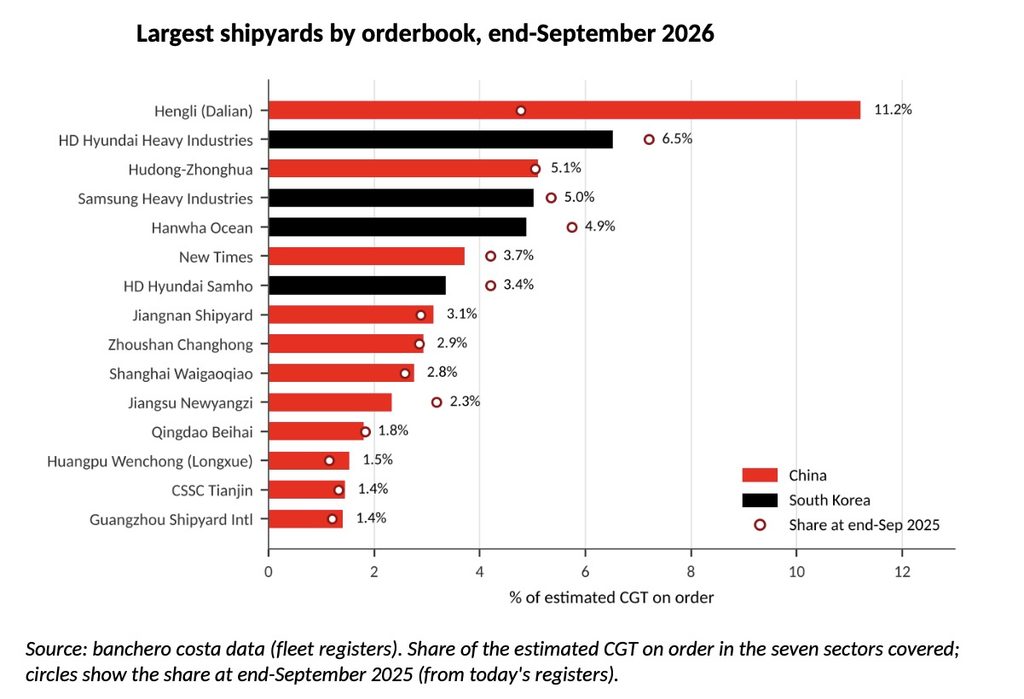
From January to September 2026, Hengli Heavy Industry undertook 276 new ships. In terms of CGT (corrected gross tonnage), it accounted for 23.4% of the new contracts signed by the world's seven largest merchant shipping sectors - almost three and a half times that of the second-placed Hudong-Zhonghua (7.1%). A year ago, it ranked fifth, with a share of 4.8%. The order book on hand rose to 485 ships in the same period, accounting for 10% of the world's new contracts by CGT. 11.2%, ranking first among single-hull shipyards. The 276 ships are composed of 117 container ships, 100 crude oil tankers, and 39 bulk carriers (Source: Splash247, citing Banchero Costa).
This is the second identity change of the shipyard in four years: it took over the bankrupt original STX Dalian in 2022, delivered 4 ships in 2024, 17 ships in 2025, and 62 ships have been delivered in the first nine months of this year. The original words of Splash247 are "brought back from the dead".
This set of figures is not isolated evidence. The semi-annual report of Songfa Co., Ltd. (603268.SH), the listed entity of Hengli Heavy Industry, disclosed that it received 207 new ship orders in the first half of 2026, far exceeding the 115 ships contracted for the whole year of 2025; 40 ships were delivered during the same period, and the delivery plan is scheduled to 2030 (Source: Songfa Co., Ltd. 2026 Semi-annual Report, Juchao Information Network). The two materials count the same thing, but the window is different - Banchero Costa counts to the end of September, and the company counts to the end of June. According to this calculation, in the third quarter, it received approximately 69 orders and delivered approximately 22 ships, which does not conflict with the caliber of the list.
Second, why is it happening now?
The shipowner placed an order to buy the future slipway. Without production capacity, there is no quotation qualification, so the ramp-up speed is the prerequisite for this round of orders - the actual delivery of 62 ships is the confidence for the new contract of 276 ships.
What supports production capacity is money and equipment. Hengli invested 13.5 billion yuan (about 1.9 billion U.S. dollars) to expand production and install two 2,000-ton gantry cranes with a span of 256 meters, the largest in the world. It also built its own production capacity for marine main engines and other key equipment (Source: Same as above). For dual-fuel ships, self-made main engines mean that the construction rhythm is not blocked by the external supply chain.
The demand side has also opened a hole. This year, 32.8% of newly signed contracts in terms of CGT went to newly built or resumption of production shipyards, the vast majority of which are in China, and Hengli took most of them (Source: Ibid.). Shipowners are willing to hand over orders to shipyards with less experience, rather than just recognizing the old ones - this is typical behavior at the high level of the cycle.
The schedule gives further information: Banchero Costa's delivery plan shows that Hengli should deliver 99 ships next year and 199 ships in 2028; in terms of CGT, it alone accounts for 12.6% of the world's seven major sector deliveries in 2028 (source: ibid.).
3. Who benefits and who loses?
The most direct beneficiary is the parent company. Songfa's 2026 third quarter report shows that the operating income in the first three quarters was 37.774 billion yuan, a year-on-year increase of 221.25%, and the net profit attributable to the parent company was 6.673 billion yuan, a year-on-year increase of 424.87%; of which the net profit attributable to the parent company in the third quarter was 3.064 billion yuan, which has exceeded the 2.655 billion yuan in 2025. The reason given by the company in the report is "the rapid growth of orders on hand, the number of ships started, and the number of deliveries have increased significantly compared with the same period last year" (Source: Songfa Co., Ltd. 2026 third quarter report, 2025 annual report, cninfo.com). Shipbuilding has changed from a burden to a source of profit.
The shipowner purchased early shipping slots. At the Monaco Maritime CEO Forum tanker session, Lars-Christian Svensen, who is also in charge of Bruton, Himalaya Shipping and OMC Tankers, said Hengli "took the world by storm" and said the ships it had delivered were "excellent" (source: ibid.). This is customer reputation, not ranking.
Korean shipyards are the direct losers in this round. On the same order list, HD Hyundai Heavy Industries 6.9%, Samsung Heavy Industries 4.2%, and Hanwha Marine 3.3% are all far lower than Hengli in terms of CGT. The share goes up and down - Hengli rose from 4.8% to 23.4% in one year, and part of the increase came from other names on the same list.
The position of China's second-tier shipyards has not improved. On the list of orders held, New Times has 3.7%, Jiangnan has 3.1%, Zhoushan Changhong has 2.9%, which is not in the same order of magnitude as Hengli’s 11.2%. Hengli’s expansion has rewritten the ranking within Chinese shipyards, not just between China and South Korea.
4. What are the differences?
The tension within this statistic is very straightforward: on one hand, it ranks first in the world in orders received (23.4%), and on the other hand, it has very few deliveries (4 ships in 2024). Both numbers are correct, but they do not measure the same thing - the order list is considered to have signed a contract, and the delivery list is not calculated until the ship is shipped out. The two will not overlap before 2028.
Banchero Costa himself quantified the risk: Hengli's 2028 production schedule is approximately equal to 3.5x its annualized production in the first nine months of this year in terms of CGT (Source: Same as above). The two sides of the same data are not contradictory, but point to completely different conclusions.
The bigger gap is at the industry level. Chinese shipyards plan to deliver 89.1 million deadweight tons of bulk carriers and oil tankers in 2028. The previous annual record was 62.6 million deadweight tons in 2011; Banchero Costa expects that some orders for 2027 and 2028 will be postponed to later years (source: same as above). The planned delivery volume is never equal to the actual delivery volume. What this statistics does not answer is: that How to fill 3.5x?
Is the order genuine? There is quantifiable evidence in the financial report: as of the end of September 2026, Songfa Co., Ltd.'s contract liabilities were 15.312 billion yuan, an increase of 186% from the 5.354 billion yuan at the end of the previous year (Source: Songfa Co., Ltd. 2026 third quarter report, cninfo.com). The contract liabilities are mainly prepayments by the shipowner based on the construction progress - the order is not a letter of intent, but the money that has been received. This article supports the side of "accepting orders is true"; but it also illustrates another thing: after the money is collected, the ship must be built.
5. Follow-up observations
The following is speculation, not proven fact.
A testable inference is that Hengli's share of orders will peak in 2027, and then fall back to around 15%, rather than continue to rise towards 30%. This is based on the dispersion instinct of shipowners - a single shipyard takes nearly a quarter of the world's newly signed contracts, and any major shipowner will take the initiative to distribute orders to the second and third companies to avoid having its shipping schedule tied up by the fluctuations in the production capacity of one shipyard. The 23.4% figure itself constitutes a reason for the decline.
The real verification point is in 2028, not this year. The order-taking ability has been proven, but the ramp-up of production capacity and quality control have not yet been achieved - 3.5x is a slope that this shipyard has never run before.
falsification signal: (1) If the delivery in 2027 is significantly lower than the planned 99 ships, it means that the slope cannot be sustained and the share will fall faster; (2) If the actual delivery in 2028 is close to the planned 199 ships, then the judgment of "peaking" is wrong and it can indeed absorb this volume; (3) The gross profit margin of the shipbuilding business. The 2025 annual report is disclosed by industry. The gross profit margin of the shipbuilding industry is 18.87%. An increase of 6.62 percentage points over the previous year (Source: Songfa 2025 Annual Report). The third quarterly report of 2026 did not disclose gross profit margin by business segment, and this level will have to wait for the annual report. If this level can be maintained throughout the year and continues to rise, it shows that the bargaining power really exists, rather than relying on low prices to grab orders; if it falls back with the increase in delivery volume, then the judgment of "share depends on price" is established.
Six, what to watch next?
First, Delivery progress in the first quarter of 2027. 99 ships is a full-year plan, and some of them can be matched in the first quarter. This is the earliest verifiable node.
second, Will the 199 ships in 2028 be publicly delayed or the order will be transferred to another factory?——Banchero Costa has announced industry delays, is Hengli among them?
third, Songfa Co., Ltd.’s shipbuilding gross profit margin. Order-taking ranking is face, gross profit margin is lizi, and the latter determines whether this round of expansion is benign or a loss-making profit.
illustrate: The main anchor point of this article is the Splash247 report (2026-10-30), and its data source is the shipbroker Banchero Costa. The financial and order sides include three announcements from Songfa Holdings (603268.SH, the listed entity of Hengli Heavy Industry): 2026 third quarter report, 2026 semi-annual report, 2025 annual report (CnInflation Information Network), which is used for cross-validation with the list data, All are first-hand documents disclosed by the issuer. Caliber reminder: Order acceptance and delivery are based on "vessel", shares are based on CGT, and finance is based on RMB; the statistical window of Banchero Costa is January to September 2026, and the company's announcement is based on the accounting period. The incomplete overlap between the two has been noted as an extrapolation; the gross profit margin is the value directly disclosed by industry in the annual report, not calculated.
Data source: Songfa Co., Ltd. 2026 third quarter report
Data source: Songfa Co., Ltd. 2026 Semi-annual Report
Data source: Songfa Co., Ltd. 2025 Annual Report
Data source: Banchero Costa (published by Splash247)
This article is based on public information and does not constitute investment advice.